Every month, close to 2,000 companies in England and Wales enter insolvency. In August, the Insolvency Service counted 1,946, much the same as July and slightly down on a year earlier. Over the past twelve months, one company in every 200 on the register has gone under.
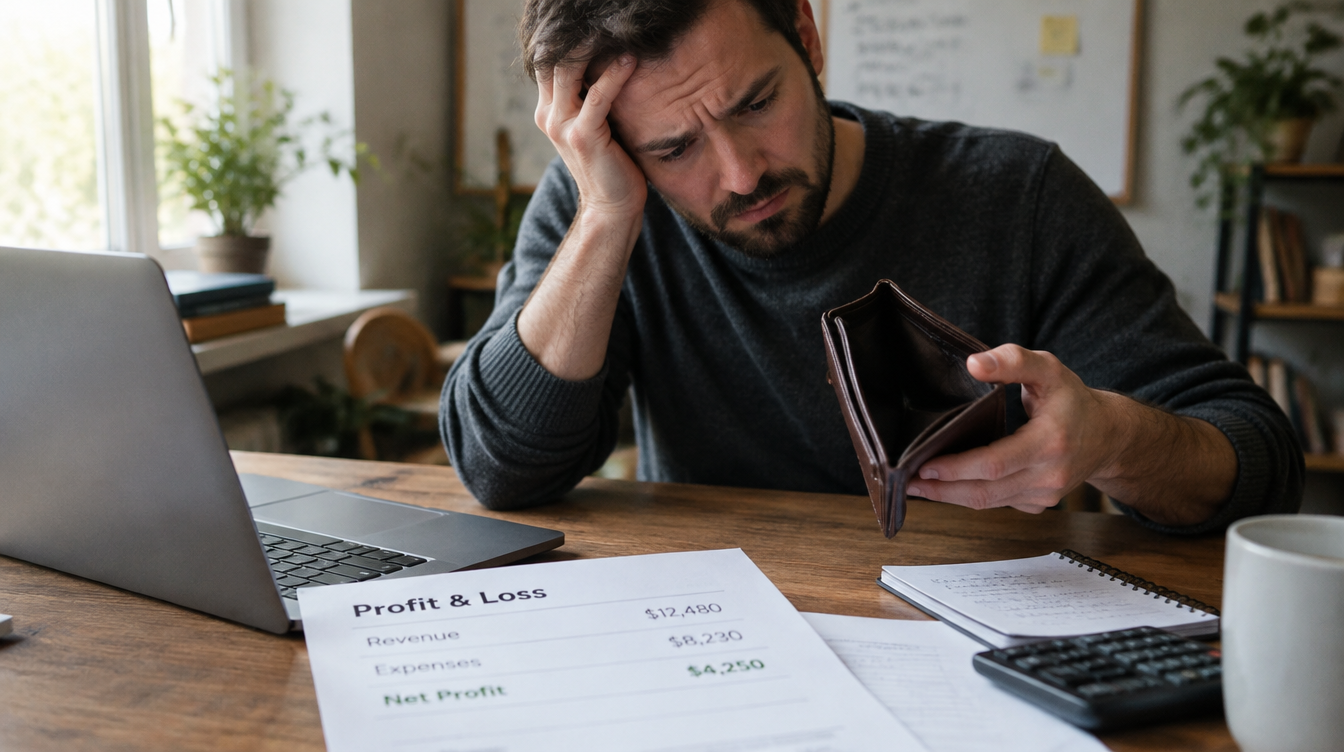
The headlines tend to follow the big names. The quieter story is how many of the rest were not, by any ordinary measure, bad businesses. They had customers, orders and often a profit on paper. What they ran out of was cash.
The Late Payment Trap
Government figures put the cost of late payment to the UK economy at £11 billion a year, and estimate that 38 small businesses close every day because they are not paid on time. The Small Business Protections (Late Payments) Bill, which entered Parliament in May, is designed to cap payment terms at 60 days and make interest on overdue invoices mandatory.
Until those rules take hold, the arithmetic is unforgiving. A firm can invoice £40,000 in March, book it as revenue, report a healthy profit for the quarter and still be unable to pay its VAT bill in May because the customer has not settled. The profit is real. The money is not in the bank.
Why Owners Find Out Late
Most small companies see their full financial picture once a year, when the statutory accounts are prepared. Private companies have nine months after their year-end to file with Companies House, so by the time those accounts arrive, the figures in them can be well over a year old.
In between, many owners run the business from the bank balance. It is an understandable habit and a misleading one. The balance shows what has already happened, not what is already committed: the PAYE payment due on the 22nd, the quarterly VAT, the supplier invoice approved but not yet paid, the client who has drifted from 30 days to 75.
What a Monthly View Changes
Larger companies deal with this through management accounts: a short set of reports, usually monthly, covering profit and loss, the balance sheet, cash flow and who owes what. Unlike statutory accounts, they are written for the people running the business rather than for HMRC or Companies House, so there is no fixed format and no filing deadline.
The useful parts are unglamorous. An aged debtors report shows which customers are paying later than they used to, often the first sign of strain further up a supply chain. A comparison of budget against actual shows a margin eroding before it disappears. A rolling cash forecast turns a vague worry about a quiet month into a specific date and a specific figure, which is something a bank can work with.
For smaller firms without a finance director, the usual route is to have a bookkeeper produce monthly management accounts from the same records that already feed the VAT return. The cost is modest next to the price of discovering a cash gap after it has opened.
Early Warning Is the Point
Most company failures are not dramatic court cases. In August, 74% were creditors’ voluntary liquidations, where the directors themselves conclude that the company can no longer pay its debts. By that stage the options are few.
Months earlier, the same numbers might have prompted a different set of conversations: renegotiating terms with a slow payer, chasing a debtor harder, trimming a cost, or arranging finance while the business still looked healthy to a lender. Insolvency practitioners say it often: the companies they can help most are the ones that call early.
The late payment reforms should ease some of the pressure. But no legislation will tell an owner that their largest customer now pays three weeks later than last year, or that the busy season they are counting on will arrive after the tax bill does. Only their own numbers can, and only if they look at them often enough.